

Wallet - Digital Cards & IDs
4.4

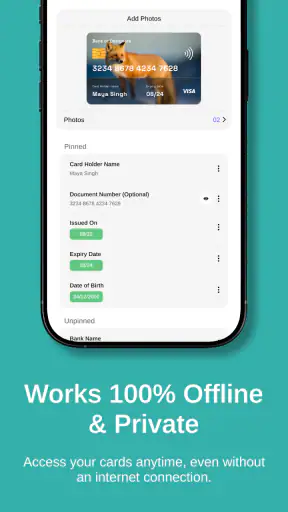
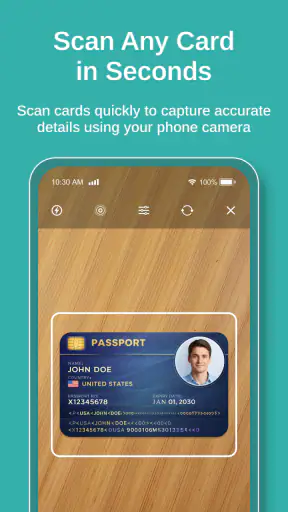
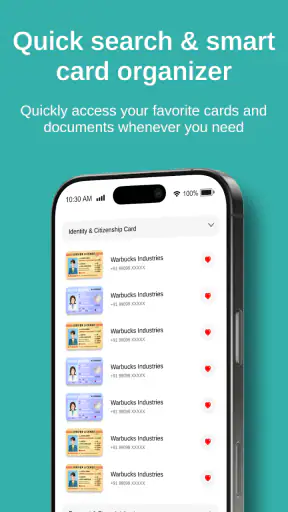
I started using Wallet - Digital Cards & IDs with a simple household problem in mind: important cards and documents are often spread across different pockets, drawers, email attachments, and separate apps. This finance app from Crady Apps brings identity documents, payment cards, loyalty cards, passports, and other records into one digital wallet. That sounds straightforward, but the real question is whether it makes everyday coordination easier without blurring personal boundaries.
After spending time with it, I see the app as a practical organizer rather than a replacement for every physical document. Its strongest value is reducing the small moments of searching and sorting that happen before travel, shopping, or an appointment. It is free, rated for Everyone, and available for devices running Android 7.0 or later. The current version is 1.0.9, and its average rating of 4.4 from around 1.4 thousand ratings suggests that the basic idea is connecting with many users.
How the wallet works in a shared household
The most useful way to think about this app is as a personal storage layer for cards and documents, not as a shared family account. In a household, several people may use the same tablet or pass a phone around while preparing for a trip, buying groceries, or looking for a membership card. That makes organization valuable, but it also makes separation important. A wallet containing one person’s passport or payment cards should not automatically become a communal drawer.
For example, imagine preparing for a weekend journey. One person needs a passport, another needs a loyalty card for a supermarket stop, and someone else wants to check a payment card before leaving home. Keeping these items in a single physical wallet can be awkward, especially when the wrong person takes it. A digital collection can make the preparation stage calmer because each item has a clear place. The benefit is less about showing a digital card at every counter and more about knowing where the relevant information is when planning.
I would still avoid treating a shared phone as a neutral family wallet. If several people use the same device, the owner should decide which items belong there. Adding another person’s documents for convenience may create confusion later, particularly when a card needs to be updated, removed, or found quickly. The app can help coordinate household tasks, but it does not turn personal documents into jointly owned records.
This distinction matters with payment cards. A household may have a shared spending card, personal cards, and old cards that should no longer be used. Putting everything together without a naming habit can make the wallet less useful than a physical card holder. I recommend labeling items in a way that identifies their purpose rather than relying only on the card design. “Groceries,” “travel,” or “personal” is more helpful during a rushed moment than several visually similar entries.
Setting up the first collection without creating clutter
The first setup is best approached as a sorting exercise. Instead of importing every card and document at once, I would begin with the items used most often. A primary payment card, a frequently visited loyalty card, and the documents needed for an upcoming trip are a sensible starting group. This makes it easier to understand how the wallet fits into a routine before it becomes a digital junk drawer.
There is a hidden trade-off in any all-in-one wallet: convenience grows with the number of stored items, but so does the effort needed to find the right one. A clean collection is therefore more valuable than a complete collection. If an item is rarely needed, keeping it in its original secure location may be wiser than adding it simply because the app accepts that type of information.
I also suggest reviewing the collection after a household event. Once a trip is over or a loyalty program is no longer used, remove what has become irrelevant. This is especially important on a shared device, where an outdated card can be mistaken for an active one. Digital storage feels unlimited, but attention is not. A smaller, current set is easier to trust.
The app’s broad purpose includes IDs, credit cards, loyalty cards, passports, and documents, so it can serve several roles at once. That breadth is convenient for someone who wants one place to start looking. However, I would not assume that storing a document digitally means every organization will accept the digital version in place of the original. For travel, official identification, banking, and regulated situations, I would continue carrying whatever physical or officially supported alternative is required.
Boundaries matter more than convenience
Household use raises a question that individual use can hide: whose information is actually being stored? My answer is simple. Each adult should keep control of personal identification and payment details, even when the same device is used by everyone. A shared device can hold selected household items, but it should not become an open archive of everyone’s private records.
This is also why I would be careful when adding passports or identity documents belonging to another person. The convenience of having them available during planning is real, but the privacy cost is higher than with a supermarket loyalty card. Before using a shared phone, I would decide whether the device is normally accessible to children, guests, or other household members. If the answer is yes, sensitive records deserve extra thought.
The app is a better fit for a personally controlled phone than for a device that circulates freely. On a personal phone, the wallet can reflect one person’s habits and priorities. On a family tablet, the same collection may need strict limits and clear agreement. This is not a criticism of the app so much as a reminder that digital organization does not remove the need for account boundaries.
Another useful habit is separating “reference” from “ready to use.” A stored image or record may help you remember a card number, identify a document, or prepare for a form, but that does not necessarily make it suitable for presenting at a checkpoint or payment terminal. I found this distinction important because a wallet app can feel more official than it actually is. It is a convenient organizer, but acceptance depends on the situation and the organization involved.
Coordinating errands, travel, and recurring tasks
Where the app feels most helpful is in preparation. Before leaving for an errand, I can think through which cards or documents might be needed and check one place instead of searching several drawers. A household member can also confirm that a particular loyalty card or travel document is available without taking every physical item out of a bag.
For a family trip, I would use the wallet as a checklist companion. The digital collection can remind me which documents must be packed, while the physical originals remain ready for situations where they are required. This workflow avoids a common mistake: assuming that digital storage alone solves travel documentation. The app helps with visibility and organization; it does not eliminate the responsibility of carrying valid originals when necessary.
For everyday shopping, loyalty cards are a more natural fit. A household can decide which memberships are used frequently and keep those easy to locate. This avoids filling the wallet with cards from shops visited once a year. If one person does most of the shopping, that person may benefit from a focused collection, while another household member can maintain a separate personal set rather than forcing both routines into one list.
I also see value in using the app during administrative preparation. When completing a form or checking an account, having relevant document details gathered can reduce interruptions. The important limitation is that convenience should not encourage careless sharing. I would open the app only when needed, avoid leaving sensitive information visible, and return the phone to its normal locked state immediately afterward.
Coordination works best when everyone knows what the wallet is for. It can serve as a household reminder system for selected cards and documents, but it is not a substitute for verbal agreement about who owns an item, who may use it, or when it should be removed. A shared device without those rules can produce more uncertainty, not less.
Age, trust, and the right person to use it
The Everyone content rating makes the app approachable in age terms, but that should not be confused with unrestricted access to sensitive information. A child may be able to understand the basic idea of a digital wallet, yet a passport, identity record, or payment card remains an adult responsibility. The age label describes the app’s general suitability, not the wisdom of placing private household records within easy reach.
For teenagers, the decision depends on what the wallet is being used to store. A loyalty card or a document needed for a specific activity is very different from giving broad access to payment details. I would introduce the organizational purpose first and keep sensitive items under the account holder’s control. That approach teaches useful digital habits without treating trust as an all-or-nothing decision.
Trust is also relevant between adults. Couples or housemates may share expenses, but sharing a device does not automatically mean sharing every card and document. The app can support a jointly planned shopping routine while still leaving personal records separate. In my view, this is the healthiest way to use it in a household: coordinate the items that genuinely need coordination and protect the rest.
Anyone who expects a wallet to handle complex family permissions should pause before adopting it as the main system. The app’s appeal is its directness, not a complicated household administration layer. If your priority is detailed separation between multiple users, a solution built specifically around managed profiles may be a better match. Here, the user has to create the boundary through device habits and careful selection.
How it compares with physical wallets and separate apps
The physical wallet still wins for immediate acceptance. A plastic payment card or original identity document does not depend on a phone being available, charged, or suitable for presentation. It is also easier to hand over a single card without exposing a whole digital collection. For those reasons, I would use this app alongside a physical wallet rather than replacing one completely.
Compared with separate loyalty-card apps, a single wallet is less fragmented. Instead of remembering which retailer uses which application, I can keep several types of card and document in one place. That is the main convenience advantage. The compromise is that a specialized service may offer a more focused experience for a particular card, while this app asks me to manage a broader collection myself.
Compared with a notes app or a folder of screenshots, a dedicated wallet feels more intentional. Random screenshots quickly lose context, and a note containing card details can become difficult to review safely. A wallet designed around cards and documents encourages better organization. Still, I would not store highly sensitive information casually just because the interface looks tidy. The quality of the surrounding device security and my own habits remains crucial.
Compared with carrying everything physically, the app is strongest before and between transactions. It helps me remember what I have, prepare for a journey, and reduce the number of cards I need to search through. It is weaker when an establishment requires an original document or a specific payment method. That division of labor makes the decision clearer: use the app for access and organization, and keep required originals available.
Small habits that make the wallet more reliable
My first practical tip is to create a short naming system before adding many items. Use the owner or purpose when that information will prevent a mistake. This is especially useful in a household with similar cards, because visual designs are not always enough to distinguish them quickly.
My second tip is to review the wallet before, not during, a stressful event. Travel mornings, medical appointments, and busy shopping trips are poor times to discover that an item is outdated or that the physical original is still somewhere else. A quick preparation check turns the app into a planning tool rather than a last-second rescue attempt.
Third, I would keep the shared collection deliberately narrow. If a device is used by several people, add only the cards and documents that truly support a common task. Personal payment cards and identity records should remain on the appropriate person’s controlled device whenever possible. This reduces accidental exposure and makes the collection easier to navigate.
Fourth, treat removal as part of maintenance. A cancelled card, expired document, or abandoned loyalty program should not remain among active items. Keeping a digital record “just in case” can be counterproductive if it makes the current item harder to identify. The wallet is most dependable when it reflects present reality.
Finally, never let the app become the only backup for something essential. If a document is needed for travel or an official appointment, confirm the accepted format and carry the required original. The wallet can make preparation more organized, but it cannot change external rules.
Who should use it and who should skip it
I would recommend this finance app to someone who carries many cards, frequently prepares for travel, or wants a clearer way to organize loyalty memberships and document references. It is also useful for a household that wants to coordinate a small set of shared items without mixing every person’s private information together. The free price makes experimenting with a focused collection easy.
I would be more cautious for someone who expects a digital copy to replace physical identification everywhere. That expectation will lead to frustration. I would also hesitate to recommend it as the central wallet on a device that is routinely passed between adults and children, unless the household has already agreed on strict boundaries.
People who prefer a minimal phone and carry only one payment card may gain little from adding another organizational layer. Likewise, users who need advanced multi-user management may prefer a service designed around separate profiles and permissions. This app is most convincing when the problem is scattered cards and documents, not when the problem is complex household access control.
Crady Apps has kept the concept easy to understand: one place for several kinds of wallet content. That simplicity is its strength, but it also means the user must supply the discipline. The app does not remove the need to decide what belongs in the collection, who should see it, or when a physical document is still necessary.
With over one hundred thousand installs, it has clearly found an audience beyond a small experiment, and the current release gives users a straightforward way to try the concept without paying. I would judge it by the quality of the routine it creates rather than by how many items it can hold. A carefully selected wallet is useful; an overloaded one is merely another place to search.
My household verdict
Wallet - Digital Cards & IDs is a sensible choice for organizing everyday cards and document references, especially when preparation and retrieval are the main frustrations. I like it most as a personal wallet with a small, intentional shared section—not as a completely open household repository.
Its best scenario is a controlled device, a current collection, and clear expectations about what digital storage can and cannot replace. Used that way, it can simplify shopping, travel preparation, and routine paperwork without pretending to solve identity verification or family account management. Used carelessly on a shared device, it may create privacy and selection problems that a physical wallet avoids.
The developer, Crady Apps, has positioned this as a free finance app rather than a complicated management system, and that focus suits the experience. I would install it for organization, keep essential originals available, and establish ownership rules before adding household documents. For readers who want a tidy digital companion to their physical wallet, it is worth trying; for readers seeking robust multi-person controls, a different kind of solution will likely be better.
4.4
24.00 Reviews
Pros
- Stores loyalty cards
- tickets
- and IDs in one organized wallet.
- Quickly displays card barcodes for convenient checkout scanning.
- Reduces the need to carry physical cards in your everyday wallet.
- Search and sorting tools make frequently used cards easy to find.
- Useful backup option for cards that support compatible digital formats.
Cons
- Not every store or organization accepts digital cards or IDs.
- Some features may depend on your device
- region
- or card provider.
- Sensitive identity data requires careful attention to privacy and security.
- Barcode scanning can fail when screen brightness or display quality is poor.
- Replacing a lost phone may require restoring or adding cards again.


